Claim Results

How Much More Do Public Adjusters Get?

How much more do public adjusters get? There is no fixed number. A Florida state study of Citizens Property Insurance claims from 2008 and 2009 found that claims with a public adjuster paid more before fees, and took longer to settle. On our own claims, the difference came from what the first estimate left out. Below are five results, including a denial we could not overturn.

  • No upfront cost
  • You always have final say on any settlement
  • CA DOI License No. 6015234

What the Carrier Offered. What We Recovered.

“Offer” is the insurer’s offer, not a payment. Each claim below started with a number that didn’t cover the loss.

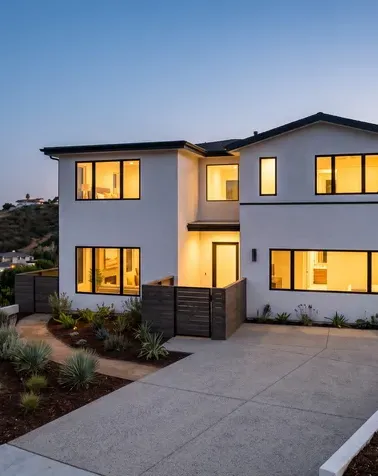
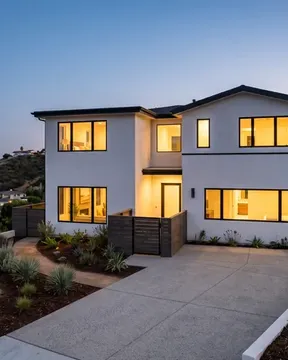
A rebuilt single-family home, finished exterior in daylight.

Los Angeles house fire, full strip out.

Offered $38,000

Settled at

$276,000

What made the difference:

structural damage properly measured, full strip out of subfloor and electrical.

Results reflect specific losses and policies. Past results don’t guarantee a similar outcome.
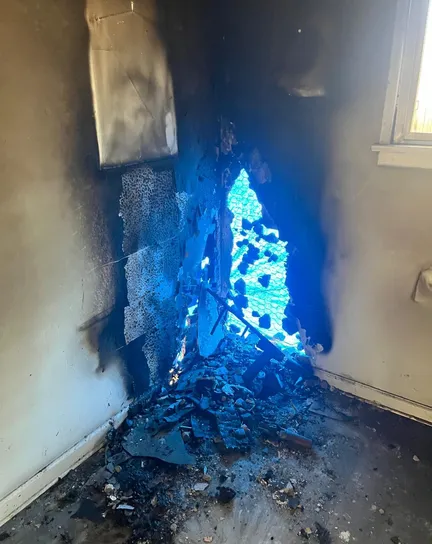
Smoke staining along the corner of a room, field photograph.

Smoke damage, home.

Offered $17,000

Settled for

about

$1.1 million

What made the difference:

an industrial hygienist proved combustion byproducts in porous materials and doors.

Results reflect specific losses and policies. Past results don’t guarantee a similar outcome.
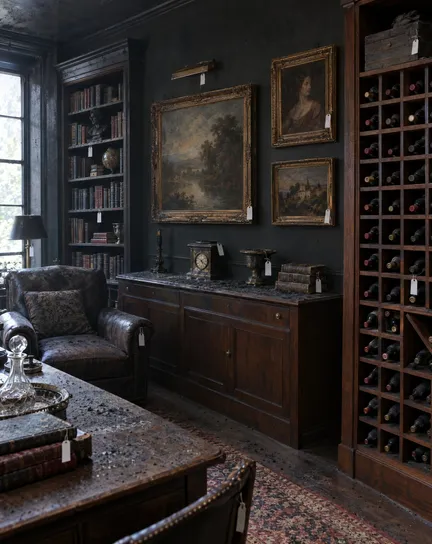
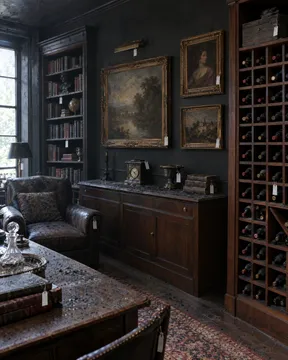
A private library with oil paintings and a wine rack under a film of soot, inventory tags attached.

Estate fire, fine wine and art.

The owner recovered $6 million on his own, then the claim stalled.

With Blue Star,

the structure settled at

$11 million, with

$5.2 million more for contents.

What made the difference:

specialist valuation of fine wine and art.

Results reflect specific losses and policies. Past results don’t guarantee a similar outcome.
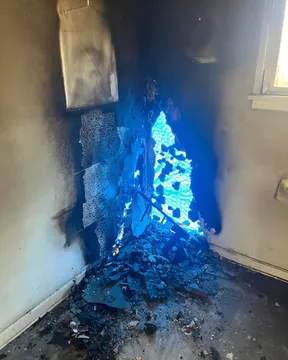
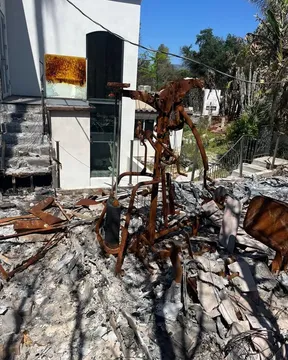
Fire-gutted interior with charred framing, field photograph.

800 sq ft apartment fire, started by a computer.

Settled for

nearly

$200,000

What made the difference:

the tongue and groove ceiling, structural repair and smoke mitigation for the neighboring unit.

Results reflect specific losses and policies. Past results don’t guarantee a similar outcome.
Garage Fire, Total Loss. Denied.

Offer denied

Result $1.4M loss, not recoverable.

What made the difference:

welding for a business in the garage. The policy excluded business operations.

We explained why before the client spent a dollar.

Some denials are wrong. This one followed the policy language. We read the exclusions at the free review, so you learn early where your claim stands. Denied or underpaid claims

Results reflect specific losses and policies. Past results don’t guarantee a similar outcome.
Results reflect specific losses and policies. “Offer” is the insurer’s offer, not a payment. Past results don’t guarantee a similar outcome.
Offered Too Little?

Bring the carrier’s estimate and your policy. We’ll tell you what it left out, or tell you the offer is fair.

Schedule a Free Review

The Florida Study. How Much More Do Public Adjusters Get Before Fees?

OPPAGA, an office of the Florida Legislature, published Report No. 10-06 in January 2010. It looked at 76,321 claims filed with Citizens Property Insurance Corporation from March 2008 to June 2009, and compared claims with a public adjuster to claims without one.

  • Catastrophe claims from Florida’s 2004 storm season, filed in 2008 and 2009. The typical payment was $22,266 with a public adjuster and $18,659 without.
  • Claims outside a catastrophe. The report estimated $9,379 with a public adjuster and $1,391 without.
  • Time to settle. Catastrophe claims with a public adjuster typically took 132 to 296 days longer. Outside a catastrophe, the median was 115 days with one and 41 days without.

Read those numbers with their limits:

  • They are before the adjuster’s fee. The report itself says the policyholder’s net would be lower.
  • One state, one insurer, and claims from 2008 and 2009.
  • “Without a public adjuster” included claims where an attorney represented the policyholder.
  • The report shows the payments differed. It does not say why. Claims that bring in a public adjuster may simply be larger or more disputed.

So a study can’t price your claim. Your policy and your damage do. That is what we measure at the free review. How a public adjuster works on your claim

When a Public Adjuster Won’t Get You More

On a small loss, or when the carrier’s offer is already fair, our fee may outweigh what we add. When an exclusion clearly applies, as in the garage claim above, no adjuster can change the policy. And no public adjuster can recover more than your policy limits allow.

The carrier doesn’t have to accept our numbers, either. We have to prove them, line by line, with the measurements, expert reports and valuations behind each one. If we can’t, we’ll say so before you sign.

Questions About Public Adjuster Results

How does hiring a public adjuster affect my claim payout?

It depends on what the insurer’s estimate missed. In the Florida study above, claims with a public adjuster paid more before fees, and took longer. On our claims, the gap came from scope: a full strip out, an industrial hygienist’s findings, a specialist’s valuation.

Is a public adjuster worth it after the fee?

Only if what we add is more than the fee. No upfront cost. We’re paid a percentage of what we recover. In California, our fee can never leave you with less than your insurer had already paid before you hired us. Public adjuster fees, explained

Will a public adjuster slow down my claim?

It can. In the Florida study, claims with a public adjuster took longer to close. Outside a catastrophe, the median was 115 days with one and 41 days without. The report notes that public adjusters may present a larger scope of damage to assess.

Does the insurance company have to accept a public adjuster’s estimate?

No. The insurer settles under the terms of your policy, not our estimate. That is why every line we add carries the measurement or the expert report behind it.

Will my claim settle for a similar amount?

No one can promise that. Each result above came from a specific loss and a specific policy. We’ll give you our honest read at the free review, before you sign anything.

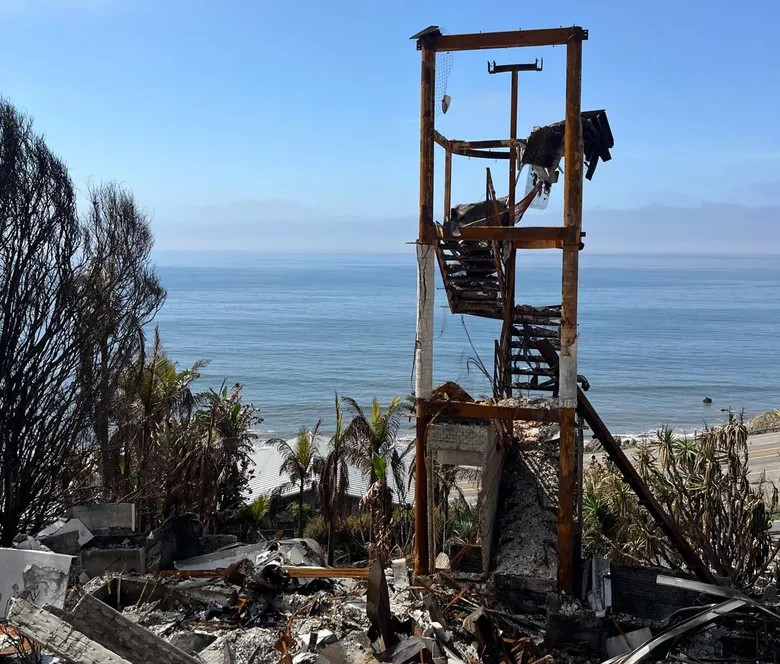
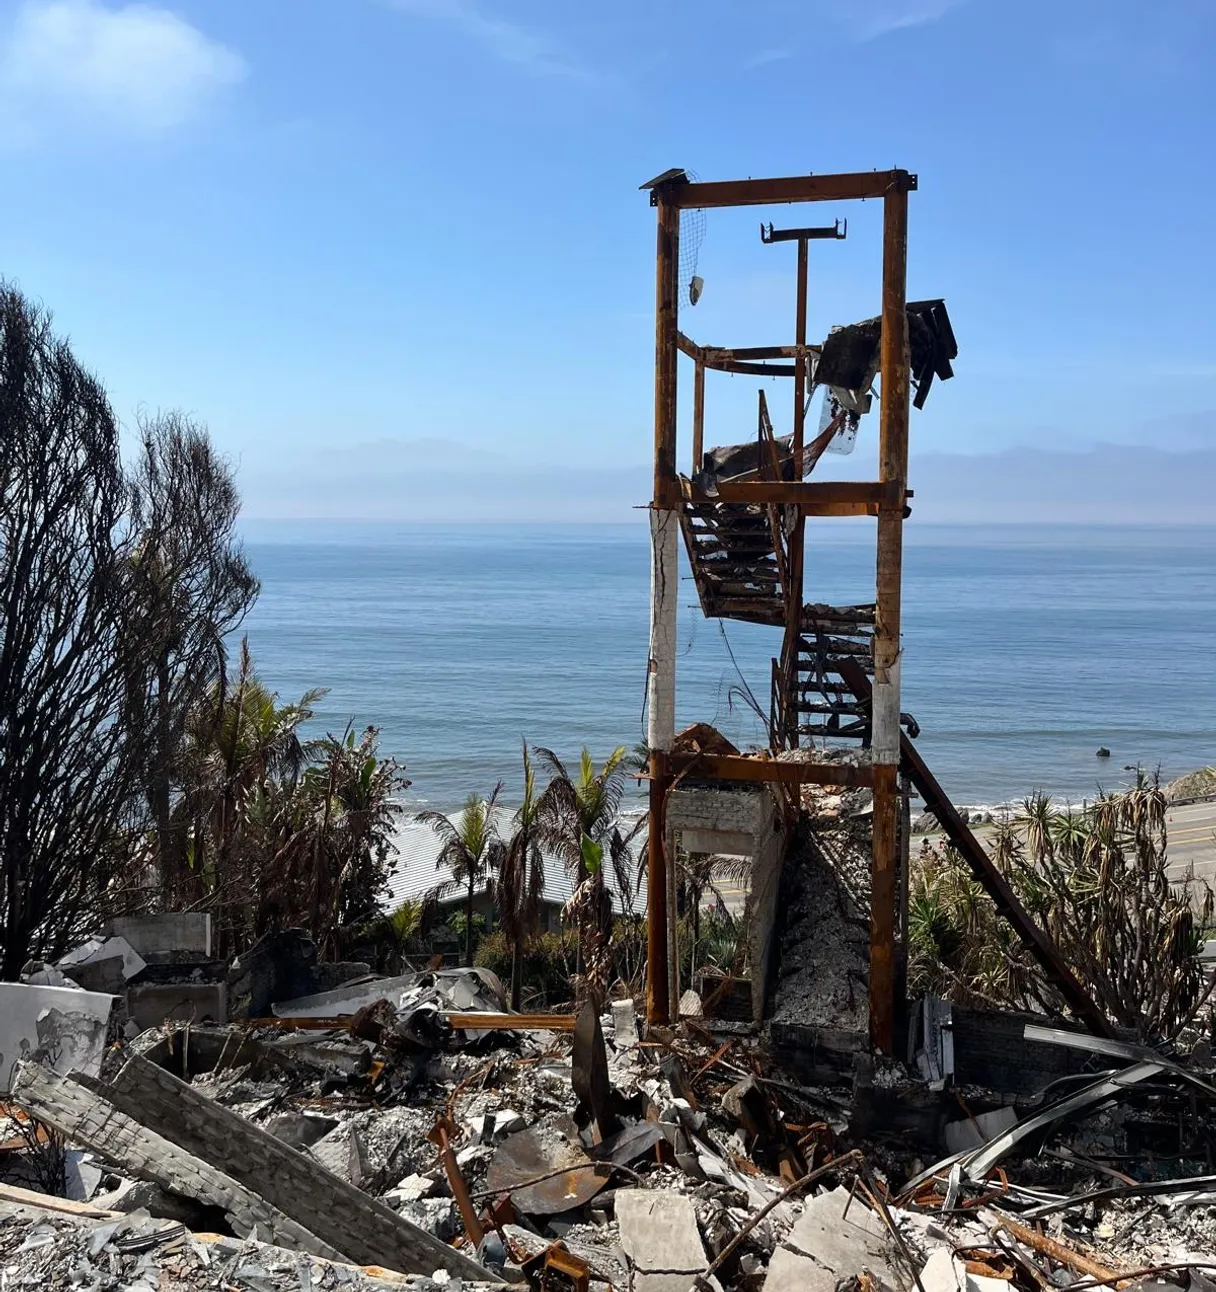
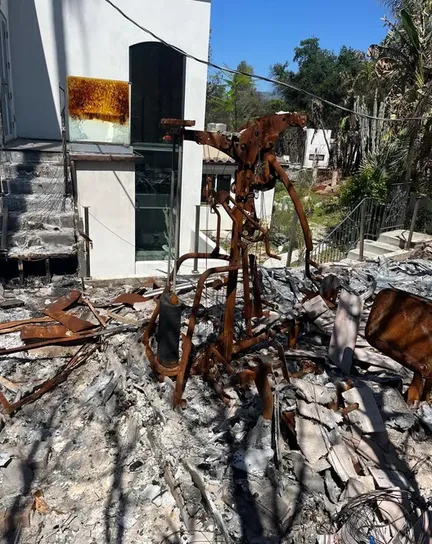
Fire-damaged coastal home reduced to its frame and rubble, field photograph.

Field photograph

Call Before the Carrier Sets the Narrative.

Your insurance company has an adjuster protecting their interests. You have the right to one too.

  • No upfront cost. We’re paid a percentage of what we recover.
  • We represent the insured only.
Call (888) 971-2524 Free Review