Fire and Smoke
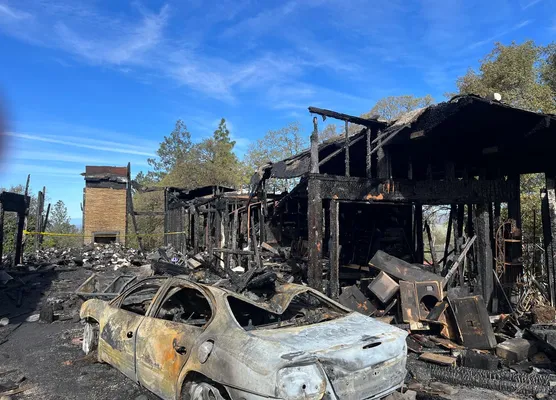
Heat Is Fire Damage. Smoke Is Chemistry.
Rooms the flames never reached, written up as undamaged.
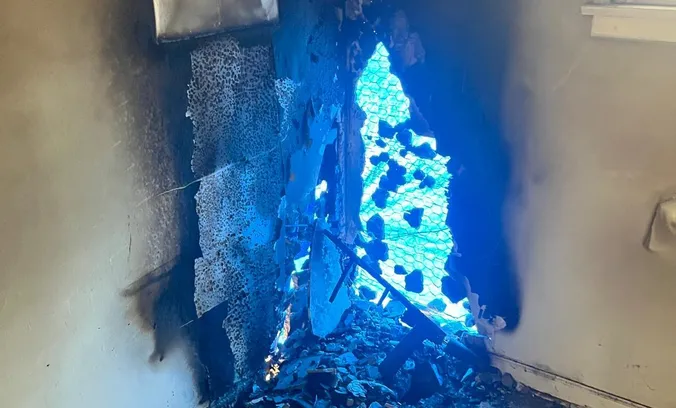
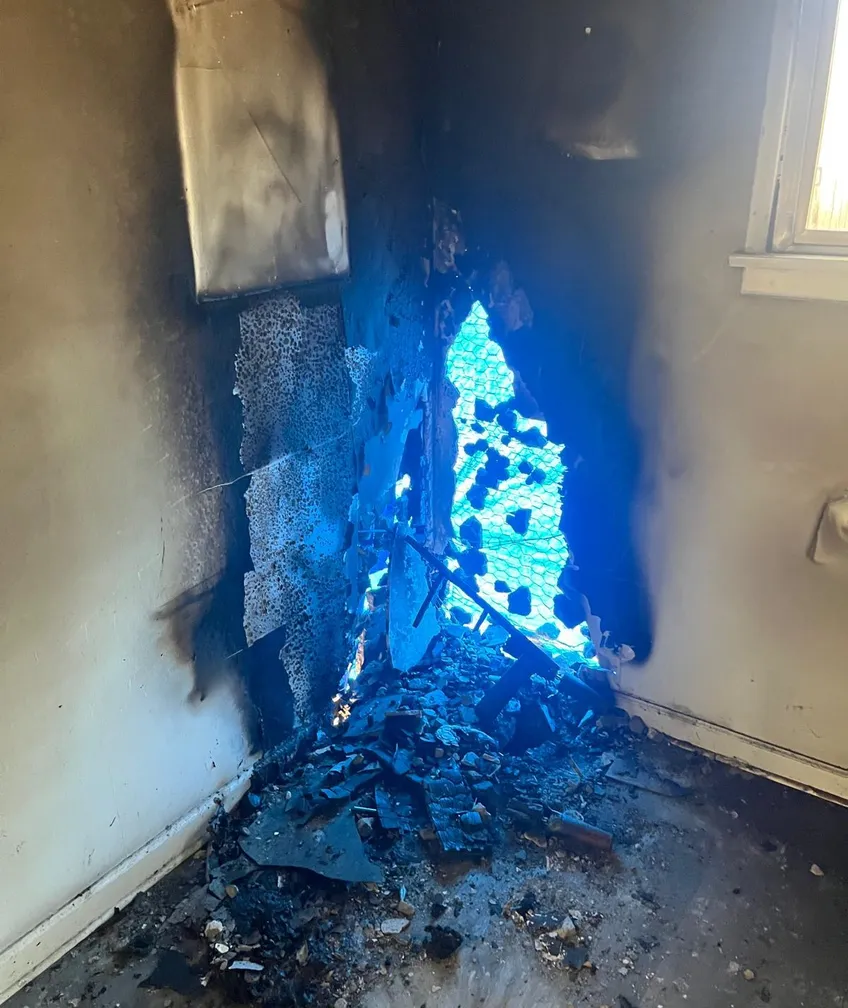
Warped vinyl windows, priced as paint.
Porous materials the carrier wants cleaned, when they can’t be.
Fire and smoke damage claimsWhat we do
Blue Star Adjusters provides public adjuster services in California, and across the other states where we’re licensed, to homeowners and businesses who need insurance claim help on a property loss. We take on fire and smoke, wildfire, water, wind and hail, lost contents, and the cost of living elsewhere while you rebuild. We read your policy, measure the full loss, build the claim and negotiate it with your insurer. A senior adjuster leads every claim, from the first call to the final settlement.
Our ability to affect your outcome diminishes with time.
Call us first, and we can look at your claim the same business day.
The estimate won’t rebuild the house.
Ordinance or law coverageThe smoke will “clean out.”
Smoke damage claimsThe water claim became a mold claim.
Water damage claimsThe adjuster changed three times.
Denied or underpaid claimsThe fine art was priced like furniture.
Contents and valuablesThe rental ends before the rebuild does.
Additional living expensesYour insurer’s adjuster already came out? Good. We start from their estimate and measure what it left out.
Home insurance claimsWhat the first estimate usually misses
Heat Is Fire Damage. Smoke Is Chemistry.
Total Loss or Standing Home. Two Different Claims.
Water Dries. The Evidence Goes With It.
Hail Shortens a Roof. A Tree Racks a House.
Everything You Owned. Accounted For.
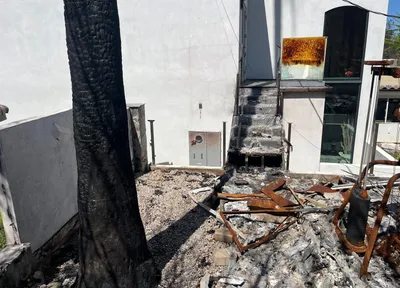
Same Size Home. Same School District.
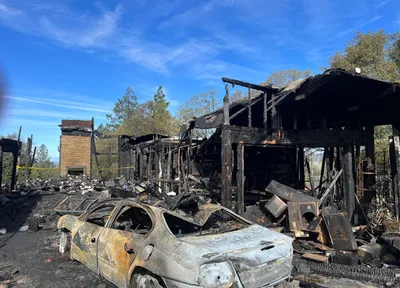
Heat Is Fire Damage. Smoke Is Chemistry.
Rooms the flames never reached, written up as undamaged.
Warped vinyl windows, priced as paint.
Porous materials the carrier wants cleaned, when they can’t be.
Fire and smoke damage claims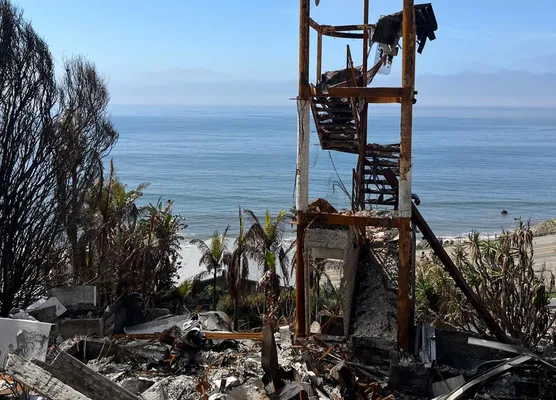
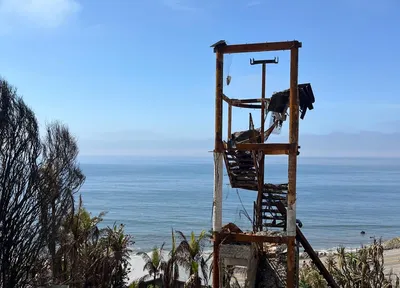
Total Loss or Standing Home. Two Different Claims.
Whether the foundation can be reused. Concrete and rebar damaged by heat often can’t carry a new house.
Code upgrades, extended replacement cost and debris removal, once the dwelling limit is reached.
Wildfire insurance claims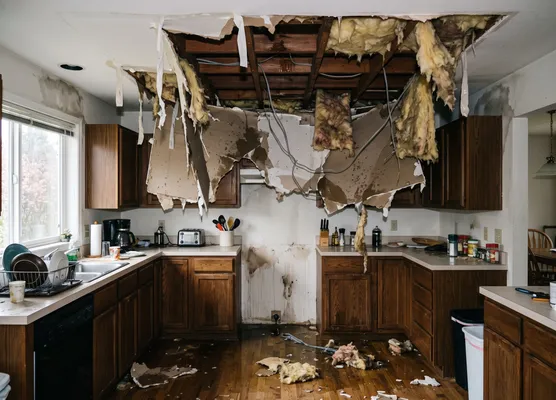
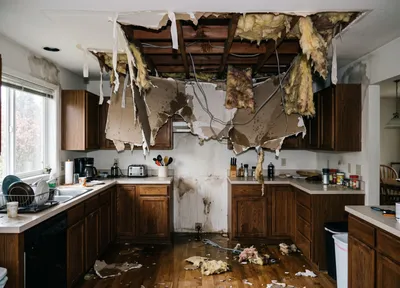
Water Dries. The Evidence Goes With It.
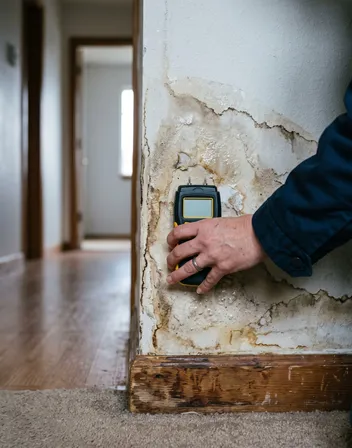
If the water isn’t measured, it dries, and mold begins to grow.
Firefighting water: after a fire, the water damage is its own line on the claim.
Water damage claims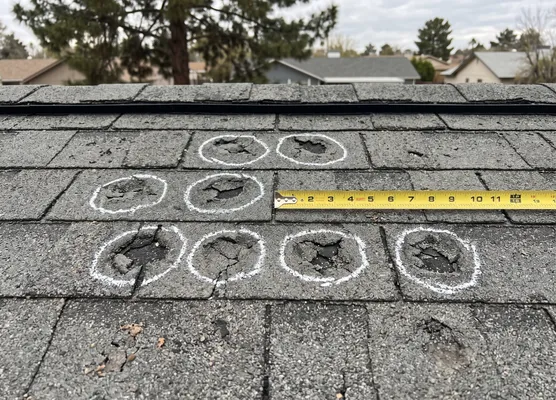
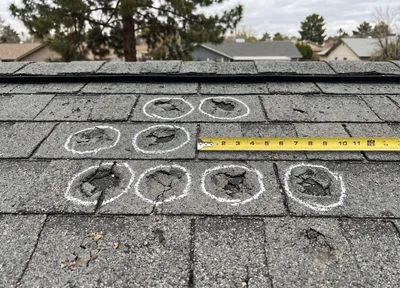
Hail Shortens a Roof. A Tree Racks a House.
Hail can take years off a roof’s life. A patch doesn’t give it back.
Framing connections, racked walls, cracks in the foundation.
Wind uplift, before it’s called wear and tear. Snow load collapse gets the same structural review.
Roof, hail and tree damage claims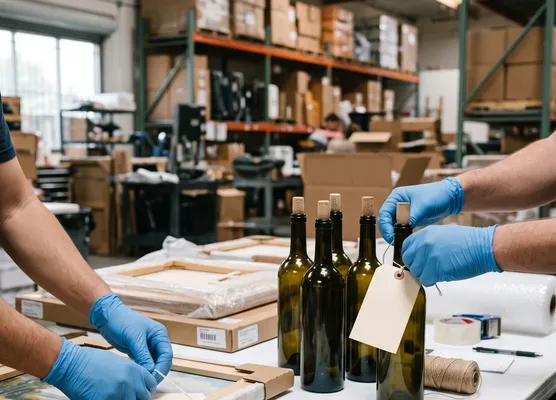
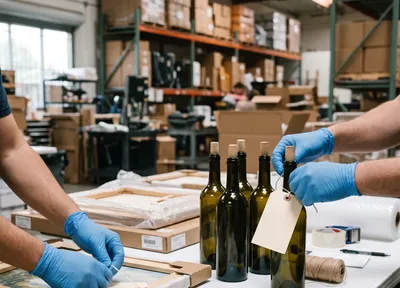
Everything You Owned. Accounted For.
Most people can’t list one room from memory, and what isn’t listed isn’t paid.
Room by room inventory built from our databases, your photos and purchase records.
The depreciation the carrier held back, if your policy pays replacement cost.
Contents and valuables claims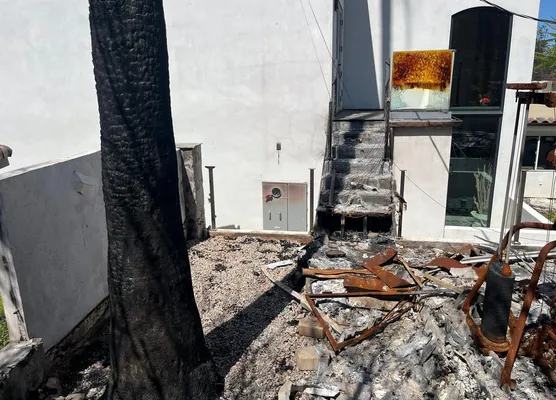
Same Size Home. Same School District.
Pet accommodations, extra mileage, meals above your normal budget, storage, utility setup.
Additional living expensesThe structure, returned to its condition before the loss and to current code.
Fences, decks, garages, barns, guest houses.
Everything inside, from furniture to fine art.
Comparable living while you’re displaced, including pet accommodations where your policy allows.
Commercial claims are more complex: more code requirements, more stakeholders, more ways for carriers to undervalue the loss.
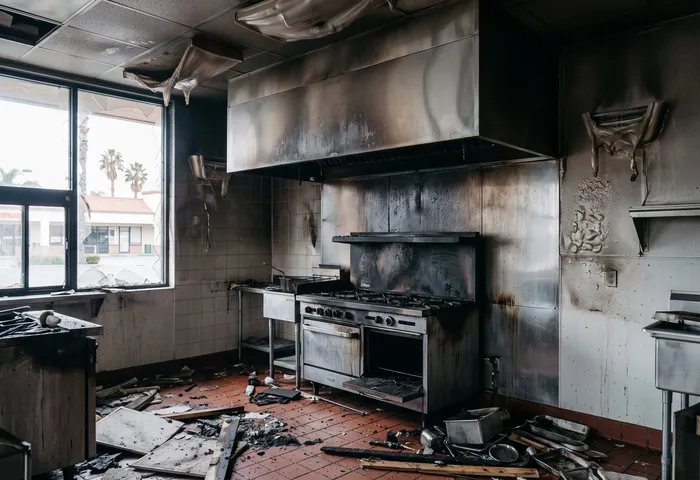
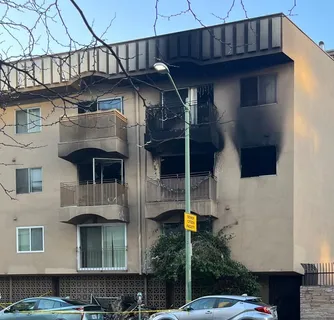
When a business burns, payroll, customers, suppliers and the landlord all wait on the same scope. We write that scope first.
Loss of income and extra expense, built from your books by a forensic accountant.
Tenant improvements vs. building: who owns what, and whose policy pays.
Inventory and equipment, at replacement cost where the policy allows.
Code: we meet building officials early, so the rebuild scope reflects what the city will actually require.
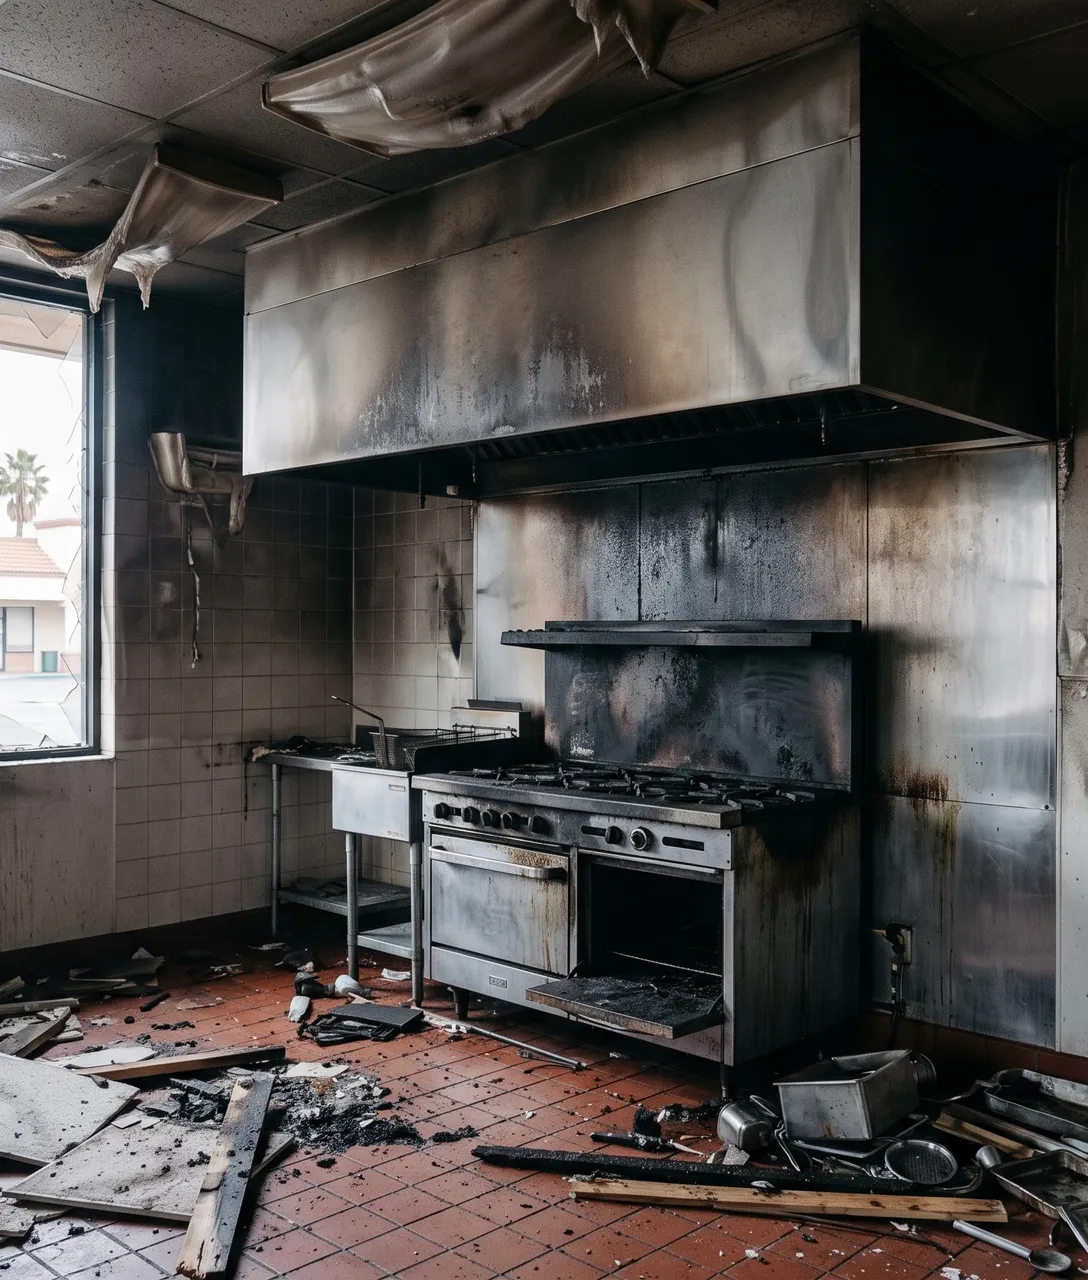
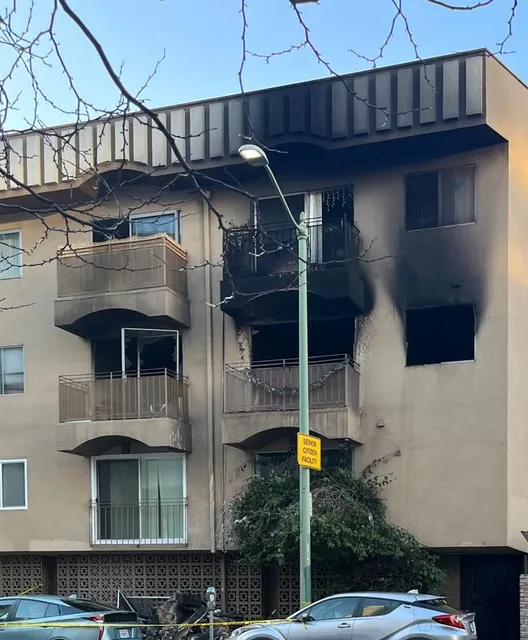
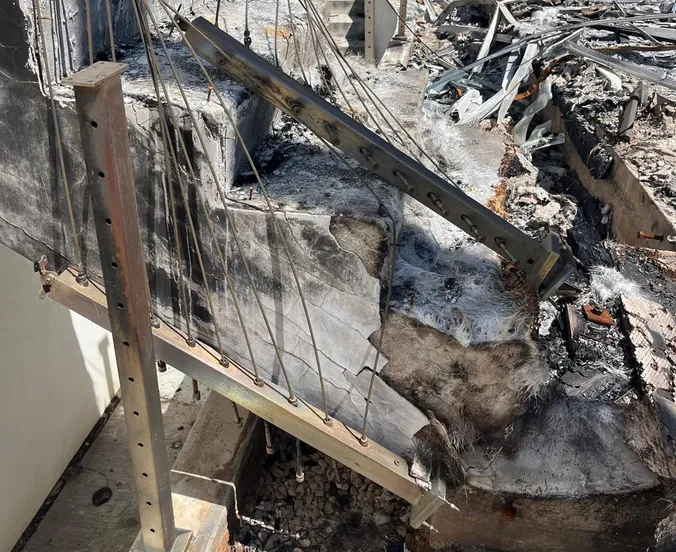
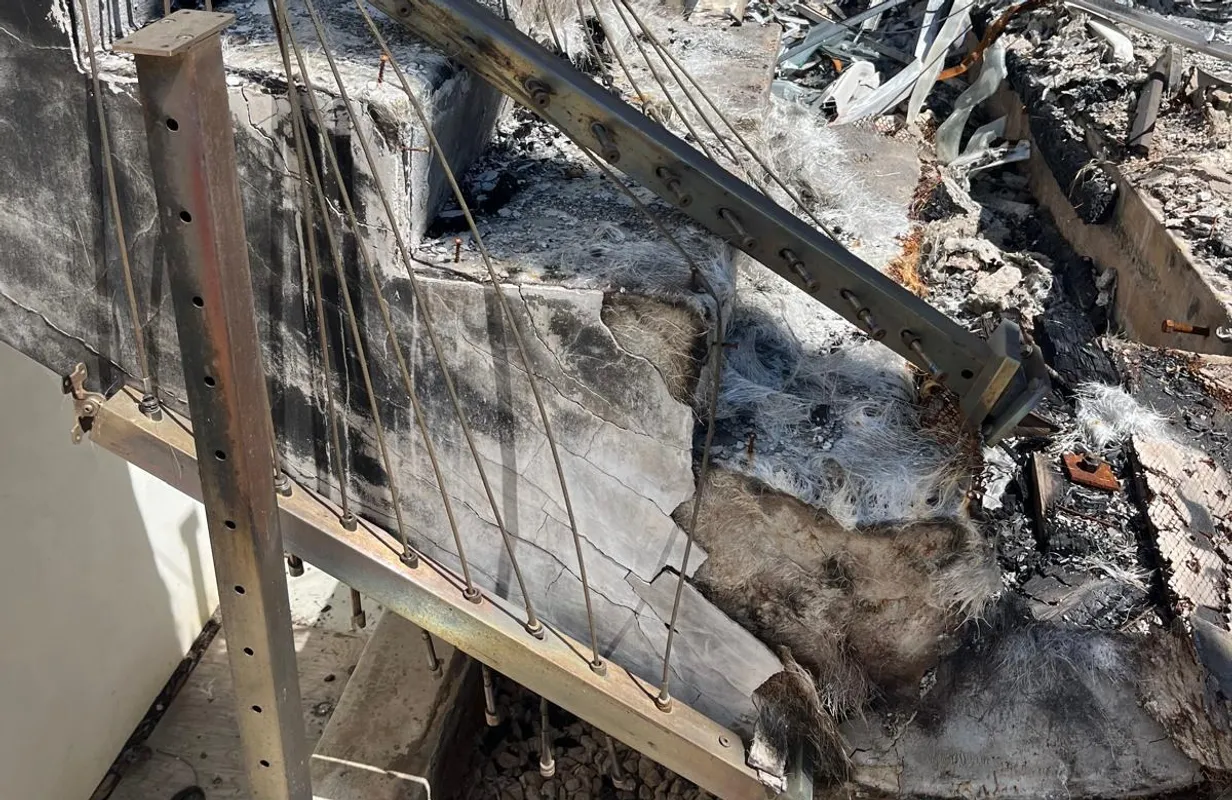
We identify and quantify code upgrade costs that may be covered under your policy, a significant source of recovery that most homeowners don’t know they have, and the carrier’s first estimate rarely includes.
What the city will require: energy code, fire sprinklers, accessibility, seismic bracing.
Undamaged portions that must come up to code because the damaged part does.
Where the money is: ordinance or law coverage (often an endorsement, with its own limit), demolition, increased cost of construction.
That limit is printed in your policy. We read it before the scope is written, so the code work is priced against money that’s actually there.
Ordinance or law coverage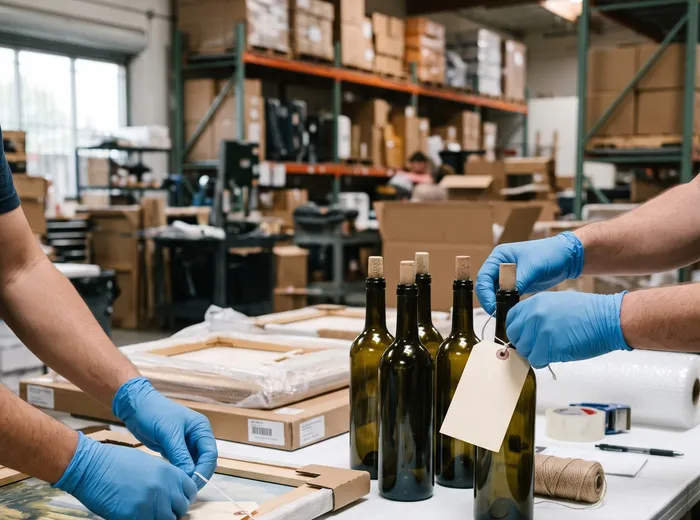
Los Angeles house fire, full strip out.
Offered $38,000
Settled at $276,000
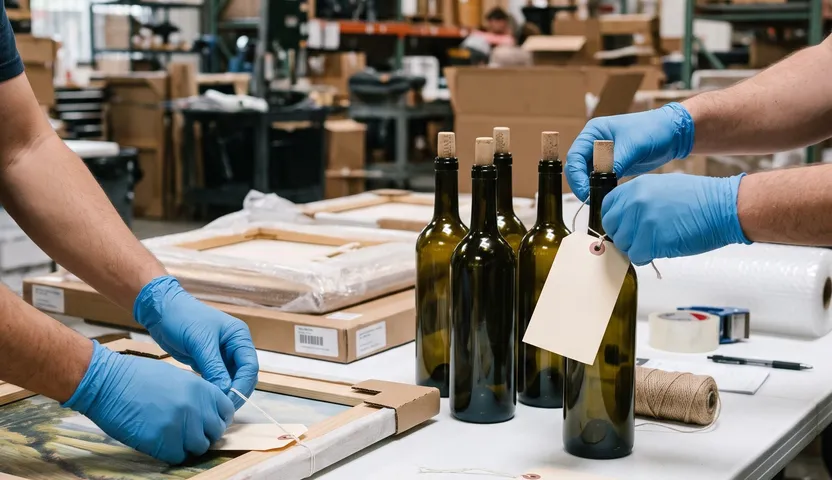
Estate fire, fine wine and art.
The owner recovered $6 million on his own, then the claim stalled on the fine wine and art. With Blue Star, the structure settled at $11 million, with $5.2 million more for contents.
Results reflect specific losses and policies. Past results don’t guarantee a similar outcome.
More claim resultsFive steps, from a free review to the settlement. You decide on every offer.
Property claims for homes and businesses: fire and smoke, wildfire, water, wind, hail and falling trees, contents and valuables, additional living expenses, code upgrades, and claims that were denied or underpaid. Each one has its own page above.
Blue Star Adjusters is licensed in California, Nevada, Oregon, Washington, Arizona and Colorado. Our California license is CA DOI License No. 6015234. In California, our offices are in Sacramento, San Francisco and Santa Monica.
Their adjuster works for the insurance company. A public adjuster is licensed to work only for you, the policyholder. We start from their estimate and measure what it left out.
Usually not. We can reopen scope before you accept. In California, our fee can never leave you with less than your insurer had already paid before you hired us.
No upfront cost. We’re paid a percentage of what we recover. The free review costs nothing, and if we can’t add value, we’ll say so.
No. We measure and negotiate. Your contractor builds.
Your insurance company has an adjuster protecting their interests. You have the right to one too.